Topic
Fintech Startups to Watch: Trends Shaping the Next Wave
Funding has stabilized, the trust gap with banks has narrowed, and the models gaining traction are the ones that sell picks and shovels to the financial system itself.
Funding has stabilized, the trust gap with banks has narrowed, and the models gaining traction are the ones that sell picks and shovels to the financial system itself.
A holder with just under 1% of CAB Payments calls the Helios Consortium's possible offer substantially undervalued and points to a competing 110p possible offer from StoneX.
Half of 270 women polled at a Sydney wealth event said they were 'writing the next chapter' of their financial lives — and the app behind the poll argues Open Banking is what makes that possible.
Banks earn the spread between deposit and loan rates, add fee income, then absorb losses and payroll; FDIC data put the industry margin at 3.32 percent in second quarter 2026.
The FDIC has paid every insured deposit since 1933. The $250,000 limit runs per bank and per ownership category, and the NCUA runs the same math for credit unions.
Acquisition spend, compliance overhead and per-account servicing costs decide whether a challenger bank reaches breakeven or keeps raising money.
Programmable payments attach rules to money, and tokenized deposits give those rules something safe to move. Here is how the two layers fit together.
Cards and wallet apps are layers of the same system, not rivals. How each works, where each shines, and how to pick the right one at the counter.
A payments hub gives merchants one integration and many payment providers. This guide explains the architecture layer by layer, from gateway to settlement.
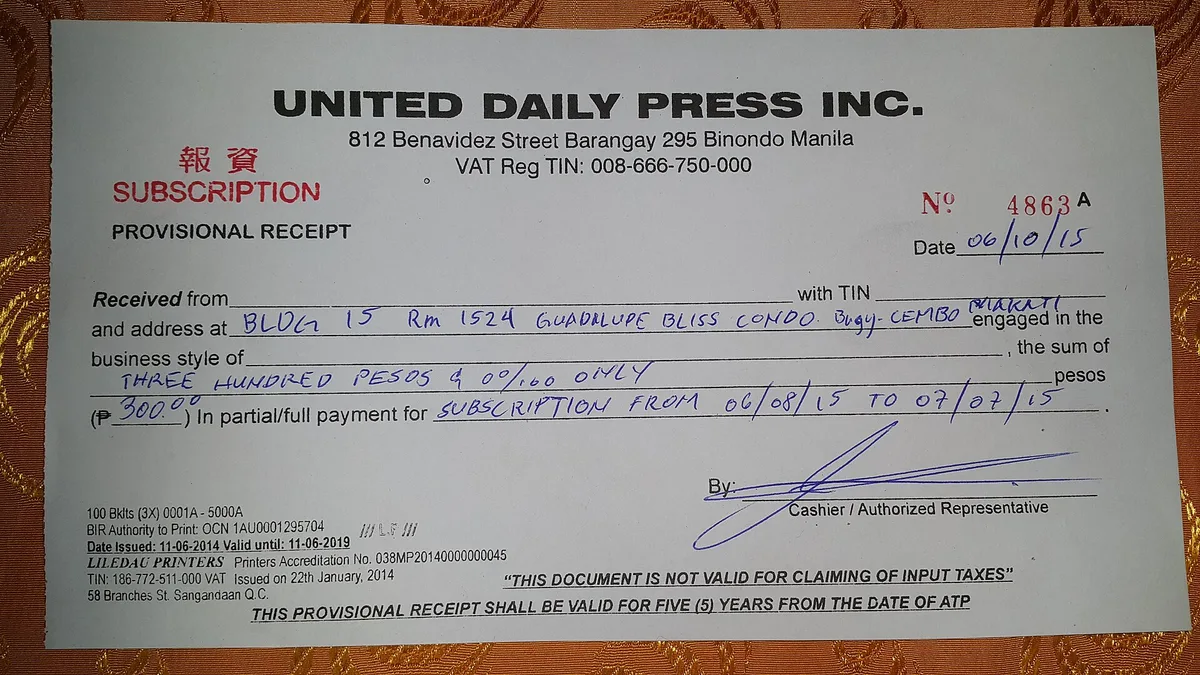
Recurring payments fade into the background until a statement surprises you. Here is a simple routine to track, rate, and manage every subscription.